

Pillar 3a Study 2026
Get a detailed overview of the2026 pillar 3a investment fund analysis as a PDF for free.
Pillar 3a investment funds and portfolios make it possible to invest for retirement in the tax-privileged pillar 3a. This comprehensive analysis from independent online comparison service moneyland.ch shows enormous differences between the 60 products included in the study. While the highest performer gained 55.5 percent over the past five years, the poorest performer made a loss of 7.2 percent.
The pillar 3a is widely-used in Switzerland. In addition to pillar 3a accounts, solutions that let you invest pillar 3a savings in stocks and other securities are also popular for long investment terms. Alongside the pillar 3a retirement funds offered by many conventional Swiss banks, there are also pillar 3a asset management services that use investment portfolios.
Online comparison service moneyland.ch analyzed the five-year net performance of 60 different pillar 3a retirement funds and investment portfolios. The evaluation accounted for both fees charged by the bank or other pillar 3a service provider, and the TER fees charged by investment funds.
The analysis covers a large portion of the Swiss market. It includes offers from six major Swiss banks with countrywide branch offices, the four largest cantonal banks, and the two leading online pillar 3a asset management services. For each service provider, moneyland.ch accounted for the funds in the fund family with the largest volume of assets under management. The analysis also accounted for products from some other service providers.
These pillar 3a funds have the best performance
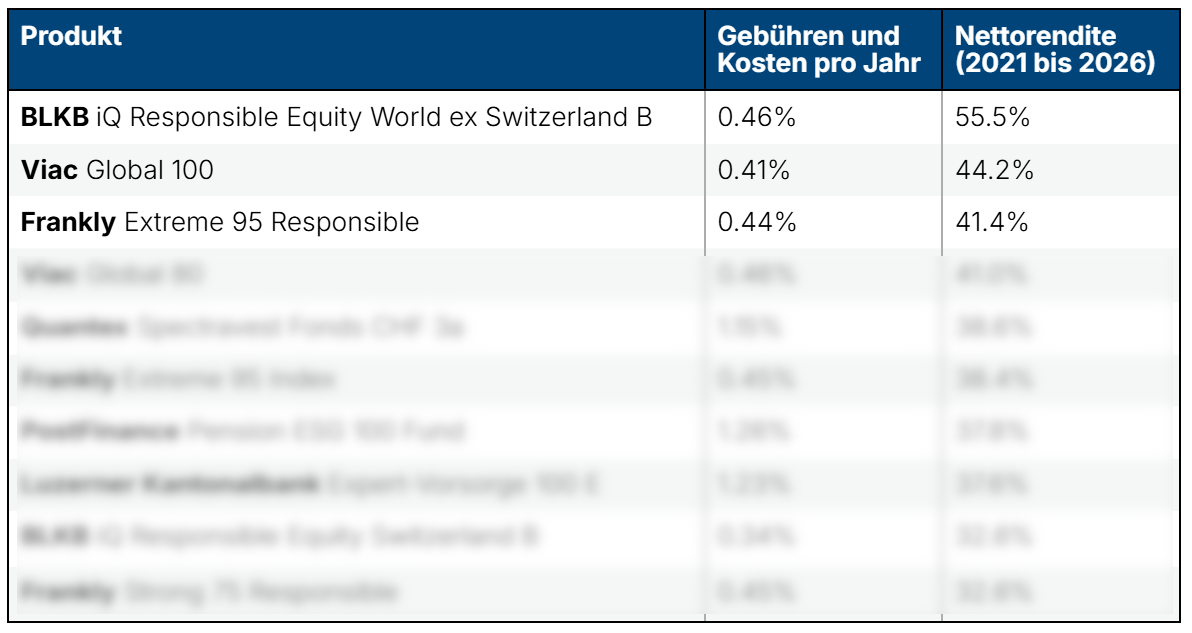
In terms of net performance over the past five years, the clear winner is a fund from the Basellandschaftlichen Kantonalbank, which gained 55.5 percent. The second place is held by a portfolio from Viac, which gained 44.2 percent. Third place is occupied by a portfolio from Fankly, which gained 41.4 percent.
“The winning fund from the Basellandschaftlichen Kantonalbank invests primarily in US stocks. These include companies like Nvidia, Alphabet, and Broadcom. These stocks gained heavily in the past five years,” says moneyland analyst Felix Oeschger.
The following 10 funds and portfolios had the highest net performance over the past five years. The analysis accounts for both the fees charged by the pillar 3a service provider, and the TER fees charged by the fund itself.
Get a detailed overview of the2026 pillar 3a investment fund analysis as a PDF for free.Pillar 3a Study 2026
Big differences in performance
The performance range across the 60 funds and portfolios is very wide. While the best-performing pillar 3a fund achieved net performance of 55.5 percent, the worst-performing fund made a loss of 7.2 percent. “Depending on your choice of retirement fund or portfolio, you could have either grown your retirement savings by a tidy 50 percent, or lost money. That shows you how important it is to choose your pillar 3a service providers and investment products carefully,” says Felix Oeschger.
The average (median) net performance is 15 percent. In other words, half of the analyzed offers gained more than 15 percent, while the other half did not.
Offers with large stock components lead
Over the past five years, the Swiss stock index SPI gained by nearly 30 percent. The MSCI World index achieved a franc-adjusted performance of 61 percent. It is hardly surprising then, that pillar 3a investment solutions with large stock components dominate the comparison results.
This pattern is particularly clear when you look at the top performers. The eight products with the best net performance all invest at least 80 percent in stocks. Developments in the US tech sector have also contributed to the favorable performance. “Most of these funds and portfolios include large tech stock components, and tech stocks have seen exceptional growth over the past five years,” says Felix Oeschger.
That is true not just for the best-performing offers. All 23 of the funds and portfolios with a stock component of at least 70 percent are among the top 30 performers.
Online pillar 3a asset management services are on the rise
The selection of pillar 3a services that are offered exclusively online continues to grow, with new service providers entering the market. Findependent became the most recent addition when it launched a pillar 3a service on October 19, 2026. Since later 2025, we have seen the Alpian, Neon, and Pilla add pillar 3a offers to their service lineups. Because these pillar 3a services have not existed for the full five-year term, they could not be included in the analysis.
The pillar 3a offer from True Wealth has only been available for just under four years. However, True Wealth’s own performance calculations for its portfolio go back further than that. The moneyland.ch analysis only includes products that have actually been available for at least five full years.
Investing in securities comes with a risk of loss
Investors should be aware of the risks. Higher potential gains come with more risk. The value of invested assets can fluctuate heavily, especially over short terms. If you find it difficult to accept these fluctuations, then it is best not to invest your retirement savings. Pillar 3a savings accounts offer more security, but the potential returns are also much smaller.
The risk of your investments losing money diminishes the longer you remain invested. But it is important to understand that losses can never be completely ruled out, even if you hold your investments for a long time. “If you still have at least 10 years to go until retirement age, and you do not plan to make an early withdrawal before that, then you can normally wait out any short-lived market dips,” explains Felix Oeschger.
Get informed with guides and comparisons
As the analysis shows, there are huge differences between offers. The interactive pillar 3a fund comparison on moneyland.ch lets you compare numerous retirement funds and portfolios based on their fees and other costs. You can also compare historical performance for the past one, three, five, and 10 years.
In addition to the many pillar 3a guides on moneyland.ch, you can also download a detailed comparison of pillar 3a asset management solutions.
Methodology
The analysis by online comparison service moneyland.ch only includes pillar 3a retirement funds and portfolios.
Period used for calculations: September 30, 2021 to September 30, 2026.
The analysis accounts for the most important Swiss banks, include six banks with countrywide branch offices (UBS, Raiffeisen, Postfinance, Migros Bank, Valiant, and Bank Cler), the four biggest cantonal banks (Zürcher Kantonalbank, Basler Kantonalbank, Luzerner Kantonalbank, Banque Cantonale Vaudoise), and the two leading online-only pillar 3a asset management service providers (Viac and Frankly). The analysis includes the family of funds from each service provider that has the largest amount of assets under management. Additionally, other products are also included in the evaluation.
The following fees are accounted for in calculations:
Net performance:
Viac is the only service provider included in the analysis that does not have its own retirement funds. Instead, it offers portfolios made up of products from third-party index funds and ETFs.


 protected by