

Retriement apps comparison
Get a free detailed overview of Swiss retirement apps and the corresponding cost simulation by email.
Managing your pillar 3a savings in an app is very convenient. But how high are the fees charged by online-only pillar 3a investment services? A new cost simulation from moneyland.ch reveals the fees charged over a period of 10 years. The costs vary between 400 and 2500 francs, depending on the service provider.
For most people in Switzerland, smartphones are a constant companion. It is hardly surprising then that savers and investors are increasingly using mobile apps to manage their pillar 3a. In addition to user-friendly interfaces, service providers also advertise low fees and charges to potential customers.
The first Swiss online-only asset management service for retirement savings was launched around nine years ago. In the meantime, the market leader Viac has grown to have more than eight billion Swiss francs under management. Frankly manages around seven billion francs of assets. But the competition in the market remains fierce, with many other service providers vying for customers.
10-year cost simulation
Independent online comparison service moneyland.ch calculated the cost of fees charged by Swiss retirement saving apps, for an investment term of 10 years. The modeled cost calculation is based on a payment of 500 francs paid into the retirement saving solution every month over a period of 10 years. The total amount paid in over the full term is 60,000 francs. The money is invested in a portfolio with a very large stock component (95 to 100 percent).
For the cost simulation, moneyland.ch accounted for both the asset management fees charged by the service provider, and the TER fees charged for the funds and other instruments used in the portfolio.
“Costs are an important factor when choosing an online retirement saving service. Fees and charges always detract from your investments, regardless of how the markets perform. There is no way to predict how the value of your investment will develop in the future. But fees and charges, on the other hand, are known and can be compared,” says moneyland.ch analyst Felix Oeschger.
True Wealth leads, followed by newcomer Findependent
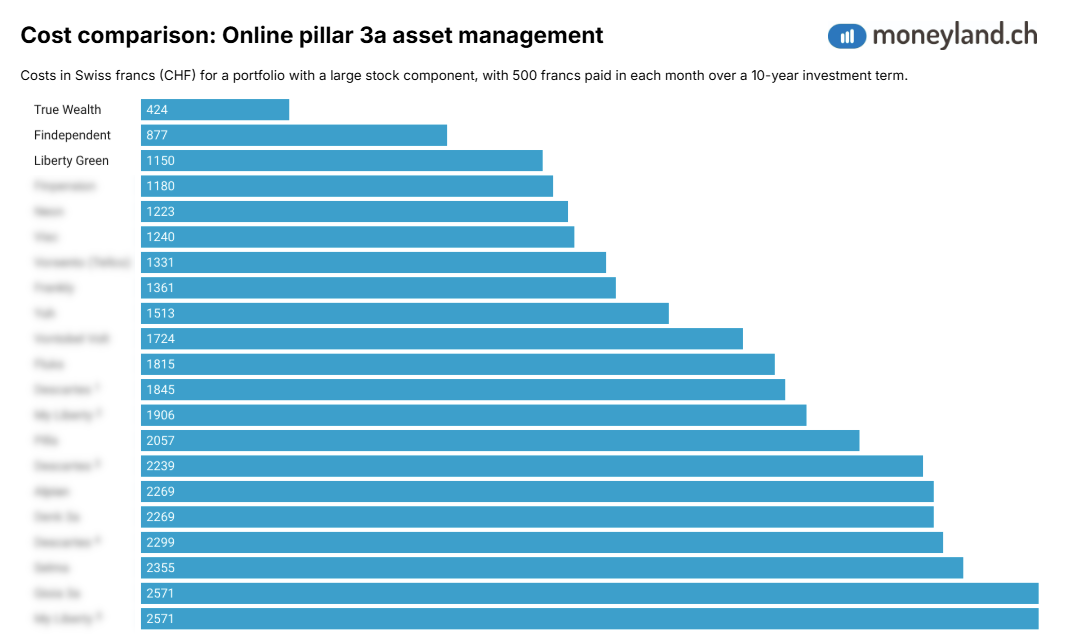
The moneyland.ch cost analysis has a clear winner: True Wealth leads by a wide margin, with total costs of 424 francs over the 10-year term. Findependent is in second place, with total costs of 877 francs. Findependent’s retirement saving service is set to launch in October this year.
Liberty Green is the third-cheapest solution, with total costs of 1150 francs. It is worth noting that Liberty Green’s portfolio is made up of only around 30 different securities. The other service providers use broadly diversified investment portfolios. “With around 30 individual securities, the portfolio from Liberty Green is much less diversified than the portfolios used by other online pillar 3a services. Most of the other service providers use ETFs or index funds, making it possible to spread your capital across numerous securities,” clarifies Felix Oeschger.
Viac and Frankly, the two largest service providers in terms of assets under management, sit in the upper third, with total costs of around 1300 francs. The graph below shows the total costs for each of the offers included in the analysis.
In addition to costs, moneyland.ch also accounted for other criteria. There are, for example, big differences between the portfolios offered by different service providers. Some online retirement saving services let you select individual ETFs or index funds to use in your portfolio. Some let you change the weighting of various components. You can get the full comparison and an overview of Swiss online-only retirement saving solutions in the PDFs available below.
Get a free detailed overview of Swiss retirement apps and the corresponding cost simulation by email.
Retriement apps comparison
2500 francs with the most expensive retirement saving apps
The fees charged by the most expensive online-only retirement saving services total around 2500 francs for a 10-year term. That is six times more than the cheapest offers.
But even the more expensive app-based services are still cheaper than many retirement funds. A comparison with conventional pillar 3a funds shows that the fees of funds offered by certain established Swiss banks can total 3000 or even 5000 francs over a 10-year term.
“Online-only retirement saving services are often cheaper than conventional retirement funds. Because pillar 3a assets typically remain invested for many years, recurring fees have a strong impact on returns, and the subsequent growth of retirement savings. That makes comparing fees exceptionally important,” says moneyland.ch analysis Felix Oeschger.
Stock investments require patience
The asset management services provided via retirement saving apps are best suited to savers who want to invest in stocks and other securities. Investing always comes with risk. The prices of assets can fluctuate. They may even fall below their original value when you bought them, for extended periods of time. Even long-term losses are impossible to rule out.
Over a long investment term of 10 years or more, the chance of losses is relatively small. The returns, on the other hand, can potentially be much larger than the interest earned from a pillar 3a savings account.
Funds without any TER fees
The 2026 analysis of online retirement saving solutions reveals an interesting market development: Investment portfolios from many service providers now include funds with TERs of 0.00 percent. This is the case with Findependent, Finpension, Fluks, Frankly, Neon, Viac, and Yuh.
For you as the customer though, it is the total, combined cost of both the asset management fee and the TER fees that matter.
Find more information in the detailed guide
The guide to online asset management services for the pillar 3a and vested benefits answers many questions about using app-based retirement saving solutions. A detailed comparison is available as a PDF.
Methodology
Online comparison service moneyland.ch analyzed the costs of pillar 3a asset management services that are offered exclusively via the Internet.
The cost simulation is based on a portfolio with a large stock component (95 to 100 percent), with a fixed payment of 500 francs being added to the portfolio every month for a period of 10 years. Cost calculations account for both the asset management fee charged by the service provider, and the fees paid for funds and other investment vehicles in the form of total expense ratios (TERs). The cost simulation uses a simplified model. The calculations do not account for growth in the value of the portfolio, other than through the fixed payments. In practice, growth in the portfolio’s value resulting from returns would result in higher costs as well.
The analysis accounts for pillar 3a solutions from these service providers: Findependent, Finpension, Frankly, Gioia 3a, Liberty Green, My Liberty, Pilla, Selma, True Wealth, Viac, Volt, and Vorsento (Tellco). Pillar 3a offers from the following neobanks are also included: Alpian, Neon, and Yuh. The analysis also accounts for other pillar 3a services that are offered exclusively via the internet: Descartes (web portal, but no mobile app), Denk 3a, and Fluks (both stand-alone offers that are accessed via the online banking portals of the St. Galler Kantonalbank and the Luzerner Kantonalbank respectively).
The analysis only accounts for pillar 3a investment services. It does not account for pillar 3a savings accounts. It also does not account for vested benefits solutions for the pillar 2. Discounts and special rates for customers that use multiple services from the same provider are not accounted for.
Custom portfolios can generate fees that are much higher than those of the default portfolios used for the analysis. That is particularly true if you use expensive investment vehicles for your portfolio.
Swiss Retirement Funds
Retirement funds of BLKB
BLKB iQ Fund - Responsible Equity
Retirement funds with low costs
3a and vested benefits
Piguet Galland retirement fund
Custody account at Vaud Cantonal Bank
3a and vested benefits
Different variants for equity component
 Deal of the Day
 Swiss retirement fund
Retirement funds of BLKB
BLKB iQ Fund - Responsible Equity
Pillar 3a Accounts
Cornèr 3a
Attractive interest rate
3a tax savings
No account management costs
pilla
At 0.65%, one of the most attractive interest rates on the market
Open an account online in just a few minutes
Investing & retirement offers
Investing & retirement offers
Discretionary Mandate
Up to CHF 100 welcome bonus
Customized portfolios & unlimited access to wealth advisor
Daily rebalancing
Findependent
CHF 4000 free of charge with code "moneyland"
Free electronic tax statement
Sustainable investments
PostFinance E-Investment Management
Digital wealth management
From CHF 5000
Direct opening possible
Saxo Bank Special Offer
Special offer: Reimbursement of brokerage fees up to CHF 200 for 90 days
Licensed Swiss bank (FINMA)
Free expert research and trading signals
Personal wealth management
Up to CHF 100 welcome bonus
Free and convenient video call
An investment strategy tailored to your goals
Current Offers
Current Offers
Discretionary Mandate
Up to CHF 100 welcome bonus
Customized portfolios & unlimited access to wealth advisor
Daily rebalancing
Swisscard Cashback Cards Amex
No annual fees
Two cards Amex & Visa/Mastercard
With cash back
Swissquote
Leading Swiss online bank with FINMA license
Free multicurrency account & low commissions
Access to more than 3 million products (shares, ETFs, crypto and more)
PKZ Insider Card Visa
Welcome Bonus of CHF 100
No annual fees forever
Double bonus with PKZ and up to 1% worldwide
UBS Banking for adults
Open and manage your account, savings account, and cards easily in the UBS Mobile Banking App
Plus KeyClub rewards program
50 CHF welcome gift
Information
About moneyland.ch
moneyland.ch is Switzerland’s independent online comparison service covering banking, insurance and telecom. More than 100 unbiased comparison tools and calculators are available on moneyland.ch, along with useful financial guides and timely news. The comprehensive comparison tools help you to find the right insurance policies, bank accounts, credit and prepaid cards, loans, mortgages, trading accounts and telecom products for your needs. The guarantee of independence applies.
Show categories
Compare Pillar 3a Accounts


 protected by